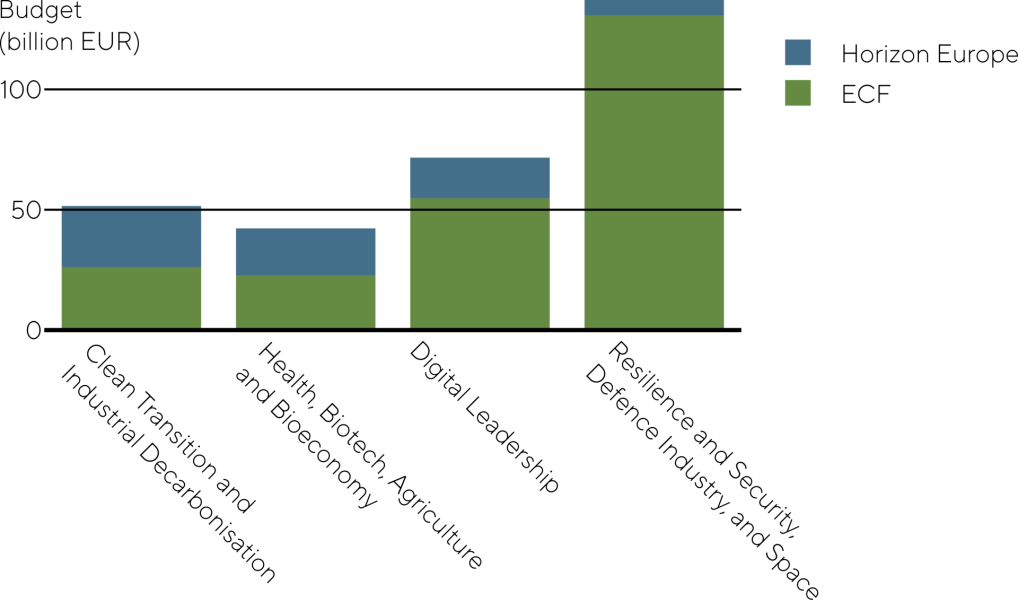Blog

Infographic

Research & development in Austria 2026: Financing and trends

5. May 2026

Thomas König &

Sarah Faber


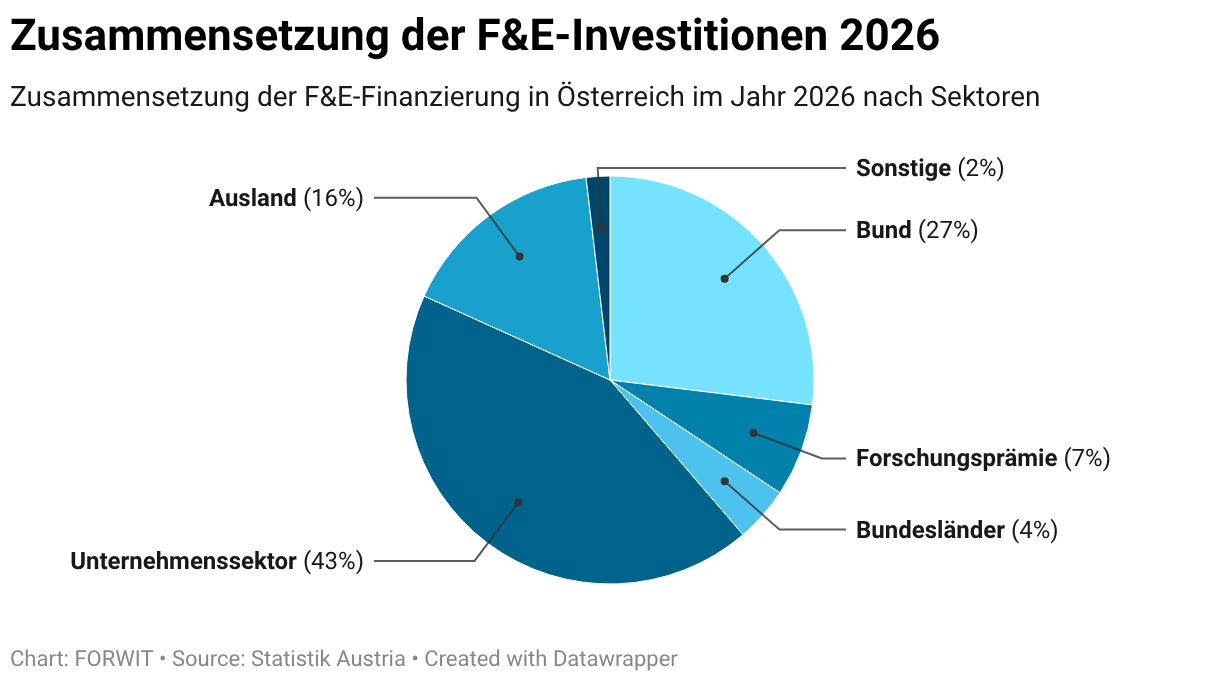
Since 2005, the R&D ratio has steadily grown. It increased from 2.39% in 2005 to 3.34% in 2026. While this still falls short of the politically set target of 4% that the federal government aims to achieve by 2030, it demonstrates that overall R&D investments have remained encouragingly stable, even—such as currently—in economically and fiscally challenging times.

The historical development of the R&D ratio since 2005 reveals long-term trends in the shares of financing sources. Business-financed R&D rises from 1.1% of GDP to around 1.4%. This development is not linear: increases are visible during economically stable phases, while declines occur in crisis years (e.g., 2009, 2020). Public financing (federal and state governments) increases from 0.78% to about 1.0% of GDP, developing somewhat more moderately but continuously.

R&D expenditures financed from abroad remain relatively stable at around 0.5% of GDP. They show no pronounced fluctuations and continuously contribute to the overall ratio. Notably, there is a significant increase in the research premium: its share of total R&D expenditures has risen from 2% (2005) to around 7% (2026), with its volume increasing roughly tenfold, while other financing sources have only doubled or nearly tripled in comparison.

Overall, the representation shows a long-term growth trend with stable contributions from multiple financing sources. Differences are primarily evident in the dynamics: while public and foreign funds remain relatively constant, business and corporate expenditures react more strongly to economic conditions.
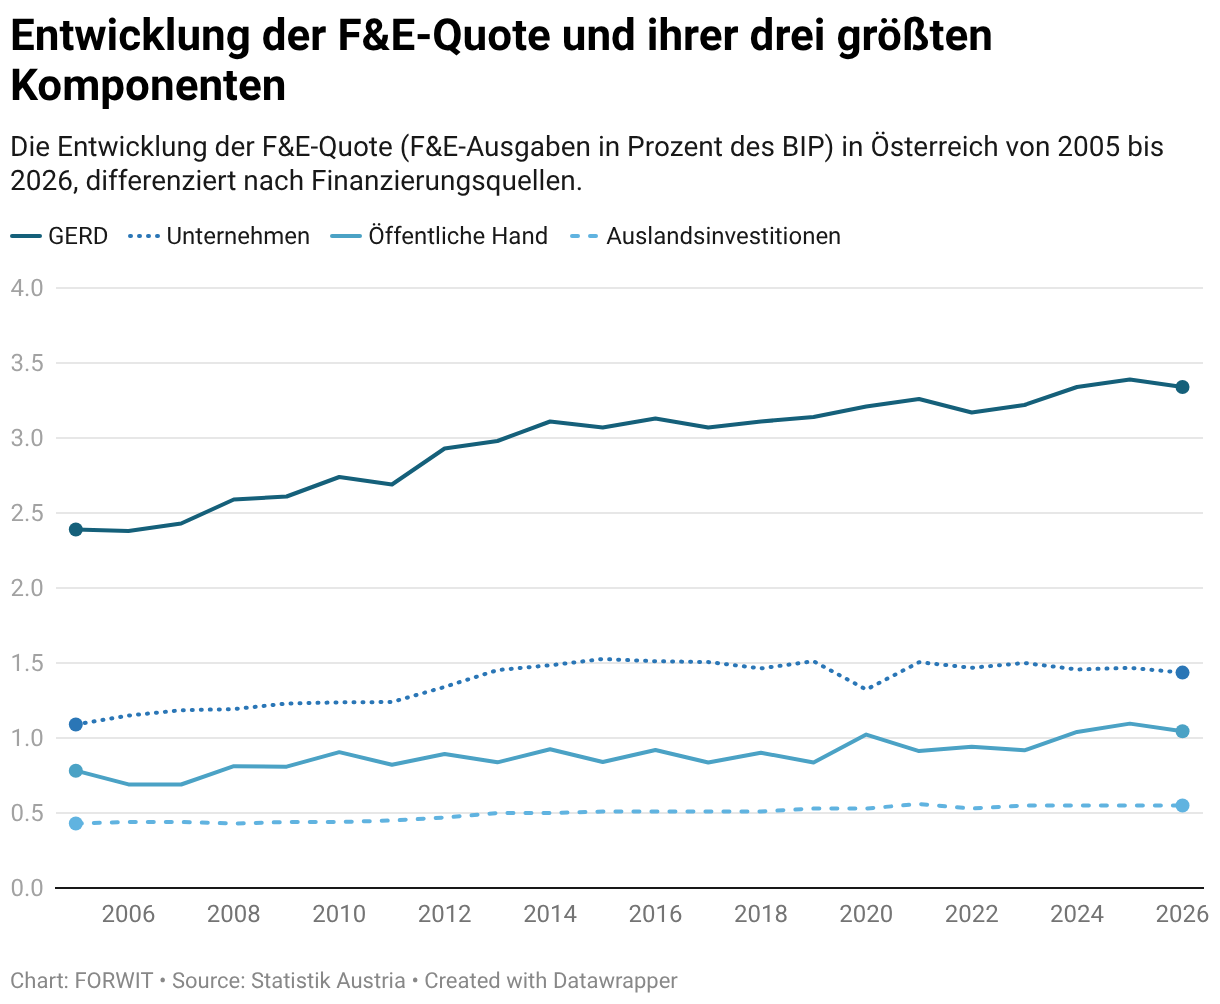


Business-financed R&D increases from 1.1% to around 1.4% of GDP. The development is not linear: Gains are evident in economically stable phases, while declines occur in crisis years (e.g., 2009, 2020). Public funding (federal and state governments) rises from 0.78% to about 1.0% of GDP and thus develops moderately but continuously.

Foreign-financed R&D expenditures remain comparatively stable at around 0.5% of GDP. They show no pronounced fluctuations and contribute continuously to the overall ratio.

Remarkable is the increase in the research premium: Its share of total R&D expenditures has risen from 2% (2005) to around 7% (2026), with a volume that has increased approximately tenfold, while other funding sources have only doubled or tripled in comparison.

Overall, the presentation shows a long-term growth trend with stable contributions from several funding sources. Differences are evident primarily in the dynamics: While public and foreign funds proceed relatively constantly, business expenditures react more strongly to economic framework conditions.

Blog

Infographic

The Austrian higher education system

13. January 2026

Thomas König &

Sarah Faber

Thomas König

Managing Director


Higher education institutions form, in a sense, the organisational framework of the higher education system. In order to gain a comprehensive overview of this system for the analysis currently being developed, we have compiled all 77 institutions in Austria, provided them with key data (date of establishment, location, number of students) and coded them according to sector affiliation. The graphic allows for a closer examination of each institution and its location within the Austrian federal territory (for institutions with multiple sites, the official headquarters is used in each case).


Unsurprisingly, most higher education institutions in each sector are concentrated in Austria’s urban centres. Nevertheless, the density of institutions in and around Vienna is particularly striking. Several institutions from different sectors are also located in Graz, Linz, Salzburg and Innsbruck. In contrast, it is primarily institutions from the universities of applied sciences and private universities sectors that are distributed across wider geographical areas.


The representation of higher education institutions on a timeline from 1955 onwards (the year in which the Higher Education Organisation Act brought consolidated legal standards into force for the first time in the Second Republic) shows that the number of higher education institutions has grown significantly over the past 20 years. In addition to a series of new foundations—particularly amongst private universities—spin-offs and retitling have also contributed to this development. As part of the university reform, the medical faculties were newly established as three independent universities. Furthermore, existing institutions were formally designated as higher education institutions: this applied both to the universities of education (known as pedagogical academies until 2005) and to the universities of the arts (known as art colleges until 2002). Among the universities of applied sciences, the FH Military Sciences is an institution that was actually founded at the end of the 18th century, was long known as the “National Defence Academy” and was formally redesignated as a higher education institution a few years ago.

The following tabular representation is particularly interesting with regard to the differences in size between individual institutions. A key indicator in this respect is the number of students. The comparison makes it clear that institutions in the private universities sector, as well as those in the universities of education sector, remain relatively small. A certain degree of homogeneity in size (by student numbers) is also ensured amongst the universities of applied sciences. The range amongst public universities presents a different picture. The University of Vienna, with 85,000 students, is almost three times as large as the University of Graz, which as the next largest institution has just under 30,000 students. At the other end of the spectrum, half of the remaining public universities have 5,000 students or fewer.


Blog

Infographic

Innovation activity declines as digital transformation progresses

16. December 2025

Thomas König &

Sarah Faber

Thomas König

Managing Director

Alexandra Mazak-Huemer &

Irfan Kačapor


Last week, the European Investment Bank (EIB) published its 2025 Investment Survey, which analyses corporate investment and identifies challenges such as digitalisation, trade and the adoption of innovative technologies. Similar to the STI Monitor, the EIB study also shows that the share of firms introducing new products and processes in their market or worldwide has been declining continuously.

In the STI Monitor, the indicator “Innovative enterprises” provides a basic breakdown by innovation status. It covers both product innovations and new or significantly improved process innovations. In addition, it takes into account, among other things, completed innovation activities, ongoing innovation projects and innovation activities abandoned shortly before implementation. The values of this indicator are based on Eurostat’s Community Innovation Survey (CIS). In the most recent CIS data collection to date (2022), Austria, with 56.7 per cent innovative enterprises, was only slightly below the average of the innovation leaders. However, the time series in the RTI Monitor points to a downward trend, which is also confirmed by the current EIB Investment Survey: it shows that investment by Austrian firms in innovation activities is declining. Firms developing or introducing innovative products stood at 43 per cent in 2023, with this share falling to 29 per cent in both 2024 and 2025.


On the other hand, it is worth highlighting that the implementation of digital technologies in Austrian companies is continuously increasing. While the share of digital technology usage stood at 82 per cent in 2023, it rose to 87 per cent by 2025. A distinction is made here between the use of a single technology (e.g. IoT sensors for machine condition monitoring) and the deployment of multiple technologies (e.g. IoT in combination with big data and AI).

It is particularly striking that Austrian companies, especially in the manufacturing sector, are increasingly opting for the use of multiple digital technologies. The use of AI is also on the rise; Austrian firms primarily deploy individual AI tools for internal processes in the fields of sales, marketing, and customer serviceConsequently, Austria ranks significantly above the EU average.

This trend is also reflected in the Artificial Intelligence section of the STI Monitor. The evaluation of indicators in the STI Monitor suggests that the use of AI is currently still limited to individual business areas and does not occur across departments. Accordingly, there has so far been a lack of strategic, company-wide integration of AI across departmental boundaries.

Blog

Infographic

FP10: Horizon Europe and the Competitiveness Fund

20. October 2025

Thomas König &

Sarah Faber

Thomas König

Managing Director

Alexandra Mazak-Huemer &

Irfan Kačapor

Bernhard Wally

Senior Policy Officer

Tile diagram of the budget of the European Competitiveness Fund, including the research framework programme “Horizon Europe”. The size of each tile is proportional to the corresponding allocated budget. Budgets with substantive links to the ECF (Pillar 2 – Competitiveness segment) are highlighted with green hatching. Sources: European Commission (2025): A Dynamic EU Budget for the Priorities of the Future – The Multiannual Financial Framework 2028–2034, pp. 9, 35. European Commission (2025): Establishing Horizon Europe, the Framework Programme for Research and Innovation, for the Period 2028–2034, Laying Down Its Rules for Participation and Dissemination, p. II-15.


On 16 July 2025, the European Commission published the first, and on 3 September 2025 the second package of its proposal for the Multiannual Financial Framework (MFF) 2028–2034. These include, among other things, proposals for the design of the next Framework Programme for Research and Innovation (FP10) and the European Competitiveness Fund, which are intended to be closely interlinked. This marks the first concrete step in the political debate on shaping the next Framework Programme.

For the MFF 2028–2034, the European Commission has proposed a total budget of €1,985 billion, of which €175 billion are earmarked for the research framework programme Horizon Europe. Based on €96 billion for the current framework programme, this represents a nominal budget increase of 83%.

In the Commission’s proposal, Horizon Europe is integrated both financially and programmatically as part of the European Competitiveness Fund (ECF), although it “remains an autonomous framework programme”. The ECF is to be endowed with a total of €409 billion, of which, in addition to the funds for Horizon Europe, €234 billion are to be made available for measures to strengthen competitiveness in four policy windows:

Distribution of the proposed budget allocations between the European Competitiveness Fund and the research framework programme Horizon Europe across the four policy windows. Sources: European Commission (2025): A Dynamic EU Budget for the Priorities of the Future – The Multiannual Financial Framework 2028–2034, p. 35; European Commission (2025): Establishing Horizon Europe, the Framework Programme for Research and Innovation, for the Period 2028–2034. Laying Down Its Rules for Participation and Dissemination, p. 24.

  • Clean transition and industrial decarbonisation
  • Health, biotechnology, agriculture and the bioeconomy
  • Digital leadership
  • Resilience and security, defence industry and space

A recent report by the FORWIT business office summarises the key elements of the Commission’s structural and budgetary proposal, highlights the main new features, and addresses remaining open issues.

Blog

Infographic

Austria’s performance in STI is stagnating

10. October 2025

Thomas König &

Sarah Faber

Thomas König

Managing Director

Alexandra Mazak-Huemer &

Irfan Kačapor

Bernhard Wally

Senior Policy Officer

Alexandra Mazak-Huemer

Deputy Managing Director


Since 2022, the FTI-Monitor has shown stagnating performance in Austria’s research, technology and innovation (RTI) system, making it clear that this is partly due to the growing gap between increasing inputs and barely rising outputs – in other words, innovation performance. This pattern is also reflected in the leading international rankings.

Recently, Austria continued to lose ground in the IMD World Competitiveness Index: while the country was ranked 16th in 2020, by 2025 it has dropped to 26th place. In contrast, countries such as Sweden and Switzerland have maintained or even improved their positions.

There is also a sideways trend visible in the European Innovation Scoreboard (EIS): although Austria remains in the group of Strong Innovators, it is ranked 8th again this year – the same as in 2020. The Innovation Leaders stand out in particular for their strong human resources, high-performing research systems, advanced levels of digitisation and robust productivity.

A similar picture emerges from the Global Innovation Index (GII), which assesses the innovation performance of 139 economies using 78 indicators: Austria has slipped from 17th to 19th place – returning to its 2020 level. Notably, China has made significant advances and has even overtaken Germany, meaning it now appears for the first time among the top 10 – despite its status as an upper middle-income economy.

Blog

Infographic

Austria 19th in the Global Innovation Index 2025

16. September 2025

Thomas König &

Sarah Faber

Thomas König

Managing Director

Alexandra Mazak-Huemer &

Irfan Kačapor

Bernhard Wally

Senior Policy Officer

Alexandra Mazak-Huemer

Deputy Managing Director

Alexandra Mazak-Huemer

Deputy Managing Director


The Global Innovation Index (GII) 2025, which assesses the innovation performance of 139 economies using 78 indicators, is topped by (1) Switzerland, (2) Sweden, and (3) the USA. South Korea has achieved its best-ever position at 4th place, scoring particularly well in terms of researchers, R&D expenditure, business-conducted R&D, researchers in businesses, and PCT patent applications by origin of inventor. China has now overtaken Germany, entering the top 10, while Hong Kong has climbed three spots to 15th place.

Austria, on the other hand, has slipped two places compared to the previous year and is now ranked 19th. Its best results are in the areas of human capital and research (9th), infrastructure (12th), and business sophistication (16th). The latter measures the share of knowledge-intensive employment, innovation linkages (e.g. university collaborations, co-publications), and knowledge absorption (such as IP payments and ICT services). Austria’s lowest rankings are in market sophistication (30th), creative outputs (23rd), and institutions, knowledge and technology outputs (21st).

Overall, Austria has improved in terms of inputs (2024: 20th; 2025: 17th) but worsened in outputs (2024: 19th; 2025: 21st). As seen in the IMD Competitiveness Ranking and the European Innovation Scoreboard, the input-output discrepancy is evident here as well. According to the GII, Austria “produces less innovation outputs relative to its level of innovation investments” – a finding also reflected in the FORWIT STI-Monitor.